Super.com-Cash Advance, Travel

Screenshots
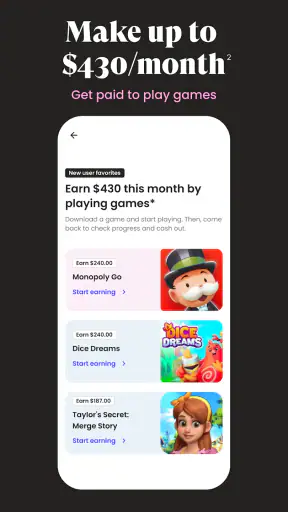
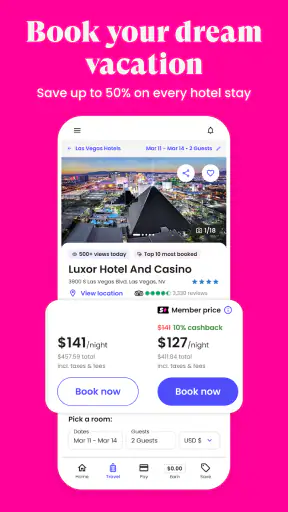
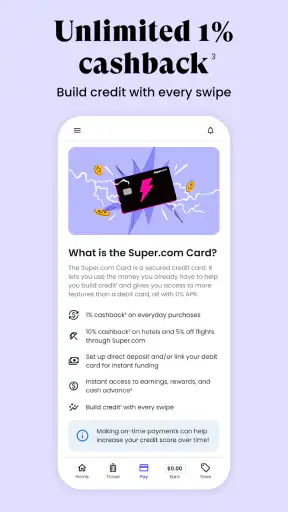
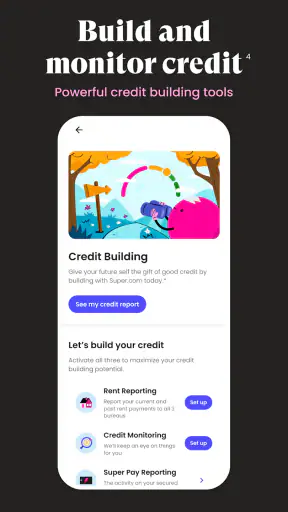
Details
- Rating
- 7.30K reviews
- Version
- 14.10.8
- Developer
- Super (previously SnapTravel)
Analysis by Norviv
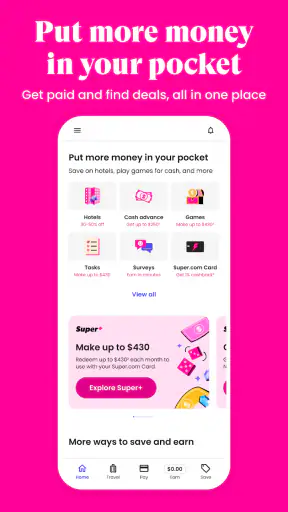
Super.com-Cash Advance, Travel is the kind of finance app that makes a strong first impression because it tries to bring several money-related tasks into one place. Instead of treating travel, saving, earning, and access to funds as completely separate jobs, it presents them as parts of one broader financial routine. I found that approach appealing during an initial look, especially if you regularly move between everyday money decisions and travel planning.
What matters, though, is whether an app like this remains useful after the novelty wears off. A busy dashboard can feel exciting for a few days and then become another icon I ignore. My experience with Super.com is best understood through that question: does it help me make better, more practical decisions month after month, or does it mainly collect attractive ideas in one convenient place?
Developed by Super, previously known as SnapTravel, the app sits in the finance category and is free to use. It has an Everyone content rating, so its presentation is intended for a broad audience. The current release is version 14.10.8 and requires at least Android 10, details worth checking before installing it on an older device.
Why the first week feels useful
During the first week, the biggest advantage is convenience. I do not have to begin with a single narrow purpose such as checking a bank balance or searching only for a hotel. The app is built around the idea that saving money, finding travel opportunities, earning more, and handling short-term financial needs can belong to the same routine. That makes it particularly interesting for someone who wants one starting point rather than several unrelated apps.
The travel side gives the experience an immediate, practical hook. Travel spending is rarely limited to the room or ticket itself; it affects the rest of a monthly budget. Having travel-related options next to broader money tools encourages me to think about the total cost of a trip rather than treating booking as an isolated purchase. That is a subtle strength, because the cheapest-looking booking is not always the easiest one to fit into real life.
I also like the way the concept can support a short planning session. I might open the app while deciding whether a weekend away is affordable, look at the travel possibilities, and then consider how that choice fits with my other financial priorities. It is more useful when I approach it as a decision-making workspace than as a source of instant financial solutions.
One realistic example is a user paid near the end of each month who wants to arrange a trip several weeks ahead. Rather than booking immediately and worrying about the consequences later, that person can use Super.com as a prompt to compare the travel idea with saving goals and available cash. The app does not remove the need for judgment, but it can make the conversation with myself happen earlier, when there is still time to change plans.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
The large existing audience also makes the product feel established rather than experimental. It has more than a million installs, an average rating of 4.5, and roughly thirty-one thousand ratings. Those figures do not prove that every user will enjoy it, but they do suggest that the format has attracted sustained attention from people looking for a broader finance app.
My first-week advice is to avoid exploring every area at once. I would start with the one problem I actually have: planning travel, finding a way to save, or understanding whether a short-term money option is appropriate. Then I would return later to the other sections. This prevents the all-in-one design from becoming an all-at-once experience.
Where it beats separate everyday tools
Compared with a basic banking app, Super.com feels broader and more discovery-oriented. A banking app is usually strongest when I need direct account management, transaction history, transfers, or a clear view of money already held. Super.com is more useful when I am exploring ways to stretch a budget or connect a travel decision with other financial goals.
Compared with a dedicated travel app, its advantage is context. A travel-only service may be faster when I already know exactly where I want to go and simply need to complete a booking. Super.com is more appealing when travel is part of a larger question: can I afford this plan, how might I save toward it, and what other money choices should I consider first?
That trade-off is important. A specialist app can feel cleaner because it does one job with fewer distractions. Super.com earns its place when the combination of functions is genuinely useful to me. If I only want a straightforward travel search or only need conventional banking, the broader layout may feel unnecessary.
The details I would check before relying on it
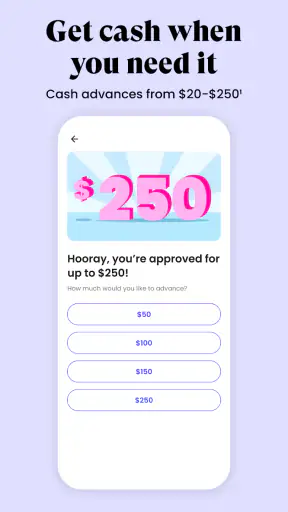
The word “advance” deserves careful attention. I would not treat a cash-advance feature as free money or as a replacement for regular income. Before using any short-term financial option, I would read the eligibility conditions, repayment timing, total cost, and consequences of missing an obligation inside the relevant screen. Those details matter more than the convenience of seeing the option in the same app as travel tools.
I would also separate discovery from commitment. Browsing a possible travel deal or a money-saving opportunity is harmless exploration; accepting a financial product or making a booking is a real decision. My practical workflow would be to note the full amount, compare it with my normal budget, and only then proceed. This extra pause is especially valuable in an app designed to make several attractive possibilities visible together.
Another useful habit is to check whether an offer solves a recurring problem or merely looks appealing in the moment. A saving feature that I can use consistently may have more long-term value than a one-time benefit that requires constant attention. Likewise, a travel option is worthwhile only if the final arrangement suits my dates, budget, and flexibility, not simply because it appeared prominently.
What remains valuable after the novelty fades
Month-to-month value depends on whether I return with a clear purpose. Super.com is not the sort of app I would open automatically every morning without a reason. Its lasting usefulness is more periodic: reviewing a travel plan, looking for ways to reduce the cost of an upcoming purchase, or checking whether a financial choice still fits my current situation.
That rhythm can be a positive thing. Finance apps do not need to become entertainment. If Super.com encourages me to pause before spending, organize a trip more carefully, or consider a saving opportunity I would otherwise overlook, opening it once or twice during a planning cycle may be enough. I would rather have a useful monthly habit than a daily habit with no meaningful outcome.
The app’s broader promise is strongest for people whose financial life includes several overlapping needs. A frequent traveler who also wants to manage short-term cash pressure may appreciate having related decisions nearby. Someone building a personal routine around saving and occasional travel can also benefit from the shared context. The app becomes less compelling for a person whose needs are already fully met by a bank, a budgeting spreadsheet, and a specialist travel service.
One non-obvious strength is that the app can act as a friction point before spending. That may sound negative, but a small amount of friction is useful when it makes me review the complete decision. Moving from a travel idea to a wider money view can stop impulse planning. I may still choose to travel, but I am more likely to do it knowingly rather than because the booking process made the expense feel detached from the rest of my budget.
A second insight is that the all-in-one design works best when I define a personal rule for using it. For example, I might use it only when planning a trip or reviewing a specific financial goal, rather than browsing every available area. This turns a potentially distracting collection of tools into a repeatable workflow. Without that rule, the app can encourage comparison without helping me finish a decision.
A third trade-off is that convenience and independence pull in opposite directions. Seeing multiple financial possibilities together saves time, but it can also make me rely too heavily on the app’s presentation. I still need an outside view of my budget and obligations. I would keep my normal banking records and personal spending plan as the final reference, using Super.com as an additional tool rather than my sole financial authority.
Who gets the most recurring value
I think the best match is someone who enjoys handling practical money tasks in one place and is willing to read the details before acting. Travelers with changing plans, people looking for saving ideas, and users who want to investigate short-term options may find enough reasons to return. The free price also lowers the barrier to trying it, although free access should never be confused with every individual financial option being cost-free.
The app may also suit someone who dislikes maintaining several separate services. If switching between a travel platform, a savings tool, and another source of financial information makes planning feel scattered, the unified approach is genuinely convenient. The benefit is not just fewer icons; it is the chance to consider related choices in the same session.
On the other hand, I would not recommend making it the center of a financial system for someone who wants highly specialized budgeting controls or a minimalist interface. A dedicated budgeting app may provide a clearer picture of categories and long-term spending behavior. A traditional bank app may be better for account administration. A specialist travel service may be preferable when speed and narrow focus matter more than financial context.
The maintenance burden of an all-in-one finance app
Every broad app asks for a little more attention than a single-purpose tool. I need to keep my expectations realistic, review the terms of any relevant offer, and avoid assuming that a feature remains useful simply because it is available. The maintenance is not necessarily technical; it is mostly mental. I have to remember why I opened the app and what decision I am trying to make.
Version 14.10.8 indicates that the product is actively presented as a current app rather than an abandoned project, but updates alone do not remove the need for careful use. I would still review important details whenever I return, especially if I am considering borrowing or committing to a travel expense. Financial products can be sensitive to timing and conditions, so a familiar screen should not encourage automatic approval.
Notifications and promotional discovery can also affect the maintenance burden. Even when an app is useful, too many prompts can turn a helpful tool into background noise. My solution would be simple: keep only the alerts that support a real goal and ignore the temptation to investigate every new possibility. The less time I spend browsing without a decision, the more valuable the app becomes.
There is also a privacy and trust dimension that I would not overlook with any finance application. I would read the permissions and account-related explanations during setup, use a strong device lock, and avoid treating convenience as a reason to skip basic security habits. These steps are not unique to Super.com, but they are especially important when one app touches travel plans and money-related decisions together.
What can cause fatigue over time
The main source of fatigue is breadth. A product that promises saving, earning, travel, and access to funds can feel generous at first, but the number of directions may make it harder to identify the one action that matters today. I sometimes prefer a focused tool that tells me exactly what it is for, even if that means using two or three apps instead.
Another possible frustration is the difference between browsing and completing a goal. It is easy to feel productive while looking at financial opportunities, but browsing does not automatically improve my finances. The app earns long-term space only when I use what I find: setting money aside, making a better travel decision, or avoiding a commitment that does not fit my budget.
Short-term cash access can create its own emotional fatigue. It may be useful in a genuine temporary gap, but repeated dependence can hide a larger budgeting problem. I would use that part cautiously and ask whether the need is exceptional or becoming a pattern. If the same pressure returns every month, a more durable budgeting solution is probably better than repeatedly reaching for a quick option.
Travel can add another layer of uncertainty. Plans change, prices move, and the cheapest initial option may not be the most flexible. I would compare the complete arrangement and read cancellation or change conditions before treating any result as a bargain. That extra work slightly weakens the promise of instant convenience, but it protects the value of the decision.
The rating of 4.5 and the roughly seven thousand three hundred written reviews show that many people have taken the time to respond to the app. I see that as encouraging, but not decisive. Finance tools are personal: an interface that helps one person organize choices may feel cluttered or too broad to another. I would use the positive reception as a reason to try it, not as a substitute for checking whether its workflow matches my habits.
My long-term verdict
After the first-week appeal fades, Super.com remains worthwhile when I use it as a deliberate planning companion rather than a financial autopilot. Its lasting value comes from bringing travel and wider money decisions into one conversation. That can help me notice trade-offs earlier, particularly when a trip, saving goal, and short-term cash concern compete for the same limited budget.
I would recommend it to a curious, self-directed user who wants a free finance app with a broad scope and is comfortable checking the details before committing. The app is especially sensible for people who travel and want their travel decisions to sit closer to their everyday financial thinking. Its Everyone rating makes it approachable for a wide audience, but responsible use still requires adult judgment around any money-related commitment.
I would skip it if I already have a reliable system that handles my budget and travel needs with less distraction. I would also avoid depending on it for recurring financial shortfalls or using it simply because an available option feels convenient. In those situations, a focused budgeting method, direct bank support, or a specialist service may serve me better.
My final view is positive but measured: Super.com earns lasting space when it turns scattered financial decisions into a repeatable planning habit. It does not replace careful budgeting, comparison, or reading terms. What it offers is a useful meeting point between travel and personal finance, and that is enough to make it worth trying for the right user. Just keep the app in its proper role—as a tool for informed choices, not a shortcut around them.
For an app that has been available since June 27, 2019, and is offered free of charge, its strongest case is not novelty. It is the possibility of returning whenever a real decision needs context. If that matches the way you manage money, Super.com can become a practical part of your routine. If you prefer every financial task to have its own specialized home, its all-in-one design may remain more interesting than essential.
Frequently Asked Questions
01What is Super.com-Cash Advance, Travel?
Super.com is a financial and travel-focused app that combines services such as cash advance access, travel deals, hotel or vacation booking options, and other member benefits in one platform. The cash advance feature is intended to help eligible users manage short-term expenses, while the travel tools are designed for planning and booking trips. Available services can vary by location, account status, and current app policies.
02How does the cash advance feature work, and who is eligible?
The cash advance feature generally allows qualifying users to request access to a portion of their expected income before payday. Eligibility may depend on factors such as income, employment information, account activity, identity verification, and other requirements determined by Super.com or its partners. Approval is not guaranteed, and users should carefully review the amount received, repayment date, optional fees, and any membership costs before accepting an advance.
03Are there fees or subscriptions associated with Super.com?
Super.com may offer certain features through a membership or subscription model, and some services can involve transaction, expedited-transfer, booking, or partner-related fees. The exact pricing may differ depending on the plan, location, promotion, and selected service. Before downloading or signing up, review the in-app pricing screens and terms carefully, especially to understand recurring charges, cancellation rules, and whether a cash advance has any optional or required costs.
04Can I use the app to book travel, and are the prices always the lowest?
The app may provide access to travel-related offers, including accommodations, discounts, or other booking benefits, depending on your membership and destination. Prices and availability can change quickly, and an advertised discount may be compared with standard or publicly listed rates under specific conditions. Before completing a reservation, check taxes, resort fees, cancellation rules, booking restrictions, and the final total, since travel policies are usually set by the individual provider.
05Is Super.com safe to use, and what should I check before downloading it?
Super.com may request sensitive information for identity verification, financial eligibility, payments, or travel reservations, so users should install it only from the official Google Play Store or Apple App Store. Check the developer name, recent reviews, privacy policy, permissions, and customer-support details before creating an account. Never share passwords or verification codes outside the official app, and contact support promptly if you notice an unfamiliar charge or account activity.


